A car may fit your purchase budget but still stretch your monthly finances. Between the down payment, loan instalments, fuel and insurance, the real cost of ownership can look very different from the showroom offer.
A car loan EMI calculator helps you estimate your monthly repayment before you borrow. Enter the loan amount, annual interest rate and repayment period, and it calculates the EMI using a standard loan formula. You can then compare different borrowing options without doing the maths yourself.
The useful part is not just finding an EMI. It is understanding how much interest you will pay—and whether a smaller monthly instalment actually makes your car more affordable.
What Is a Car Loan EMI Calculator?
A car loan EMI calculator is an online tool that estimates your equated monthly instalment: the regular payment towards your loan’s principal and interest.
It normally needs three inputs:
| Input | What it means | Example |
|---|---|---|
| Loan amount | The amount you borrow | ₹8,00,000 |
| Annual interest rate | The yearly rate used for the calculation | 9% |
| Loan tenure | The repayment period | 5 years or 60 months |
The standard EMI calculation uses these three inputs. Total repayment and total interest can then be calculated from the resulting EMI.
Treat the result as a planning estimate, not a loan approval or personalised interest-rate offer.
How Does a Car Loan EMI Calculator Work?
1. It uses the amount you actually borrow
The loan amount is not necessarily the car’s full price.
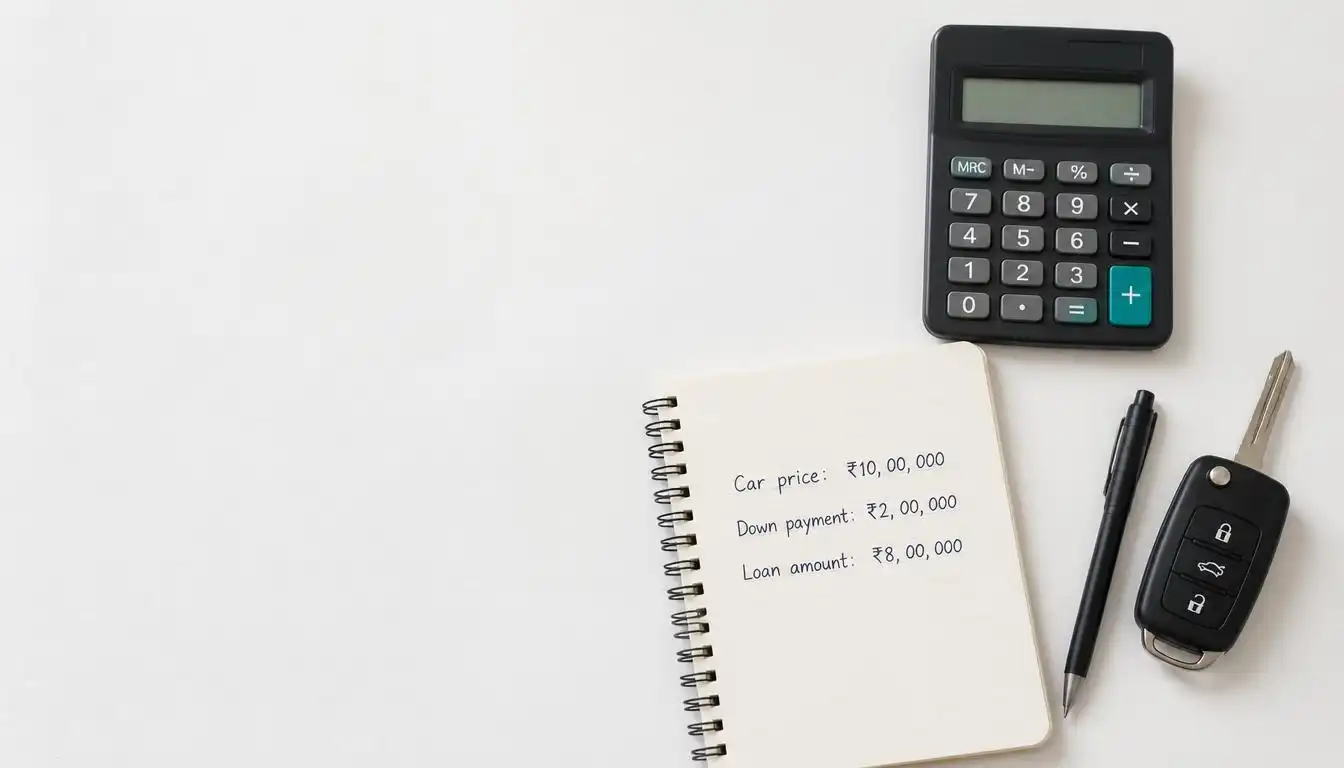
Suppose your chosen car has an on-road price of ₹10 lakh. You contribute ₹2 lakh and plan to borrow the remaining ₹8 lakh. Enter ₹8 lakh into the calculator.
For this example, assume you pay any additional loan charges separately. If your final borrowing includes financed charges or other costs, use that actual loan amount instead.
2. It converts the annual rate into a monthly rate
The EMI formula requires a monthly interest rate expressed as a decimal. At an annual rate of 9%, the calculation is:
r = 9 ÷ (12 × 100) = 0.0075
That is 0.75% per month. The calculator also converts a five-year tenure into 60 monthly payments.
3. It applies the EMI formula
The standard car loan EMI formula is:
EMI = [P × r × (1 + r)n] ÷ [(1 + r)n − 1]
- P is the principal or loan amount.
- r is the monthly interest rate expressed as a decimal.
- n is the number of monthly instalments.
You do not need to memorise this formula. Understanding the inputs is enough to use the calculator sensibly.
4. It helps calculate total borrowing cost
Once you know the EMI:
- Total loan repayment = EMI × number of instalments.
- Total interest = total loan repayment − original loan amount.
These figures cover the principal and interest in the calculation. They do not automatically include fees or other costs.
A Practical Example: ₹8 Lakh Car Loan
Consider this illustrative loan:
- Loan amount: ₹8,00,000
- Annual interest rate: 9%
- Tenure: 60 months
- Assumption: unchanged rate, regular monthly repayments and no additional financed charges
Applying the standard formula gives:
| Result | Approximate amount |
|---|---|
| Monthly EMI | ₹16,607 |
| Total repayment | ₹9,96,401 |
| Total interest | ₹1,96,401 |
Figures are calculated before rounding the monthly EMI, so multiplying the displayed rounded EMI may give a slightly different total.
The 9% rate is an illustration, not a current lender quote. Use the rate offered to you when comparing actual loans.
How Your EMI Repays Principal and Interest
An EMI is not split equally between principal and interest throughout the loan.
Under the reducing-balance calculation, each month’s interest is calculated on the outstanding principal. The rest of that month’s EMI reduces the balance. This repayment breakdown is called an amortisation schedule.
For the same ₹8 lakh example:
| Month | EMI | Interest portion | Principal repaid | Remaining principal |
|---|---|---|---|---|
| 1 | ₹16,607 | ₹6,000 | ₹10,607 | ₹7,89,393 |
| 2 | ₹16,607 | ₹5,920 | ₹10,686 | ₹7,78,707 |
| 3 | ₹16,607 | ₹5,840 | ₹10,766 | ₹7,67,941 |
Amounts are rounded individually.
As the balance falls, the interest portion falls and more of the unchanged EMI goes towards principal. Ask for your lender’s amortisation schedule to see the actual repayment breakdown; RBI’s Key Facts Statement requirements include this schedule.
How Loan Tenure Changes Your EMI
A longer tenure reduces the monthly payment, but it increases total interest when the loan amount and rate remain unchanged.
Here is the comparison for ₹8 lakh at 9% annually:
| Tenure | Approximate EMI | Total interest | Total repayment |
|---|---|---|---|
| 3 years | ₹25,440 | ₹1,15,832 | ₹9,15,832 |
| 5 years | ₹16,607 | ₹1,96,401 | ₹9,96,401 |
| 7 years | ₹12,871 | ₹2,81,186 | ₹10,81,186 |
Moving from five years to seven years lowers the EMI by about ₹3,735, but adds roughly ₹84,785 in interest.
Use this comparison to find a comfortable repayment period—not simply the lowest displayed EMI. A shorter tenure is useful only if you can manage its payments without repeatedly dipping into savings.
How to Use a Car Loan EMI Calculator Effectively
Step 1: Work out your realistic borrowing amount
Start with the written on-road quotation. Decide your down payment, then identify the amount you actually need to finance.
Keep your emergency savings separate when deciding how much cash to contribute.
Step 2: Enter a relevant interest rate
Use the rate in your lender’s offer when available. If you are still researching, label your chosen rate as an assumption rather than treating it as guaranteed.
Step 3: Compare at least three tenures
Try three, five and seven years where relevant to the available loan options. Record both the monthly EMI and total interest.
Step 4: Test a larger down payment
At 9% over five years, reducing the loan from ₹8 lakh to ₹7 lakh lowers the estimated EMI from ₹16,607 to ₹14,531.
That extra ₹1 lakh upfront reduces monthly repayments by about ₹2,076 and saves approximately ₹24,550 in interest.
Step 5: Add ownership expenses
Build a separate monthly car budget:
- EMI
- Fuel or charging
- Parking and tolls
- An allowance for servicing, tyres and repairs
- An allowance for insurance renewal
Judge affordability using this combined amount, not the EMI alone.
What the Calculator Does Not Tell You
Fees can change the overall cost
A basic calculator using only principal, rate and tenure does not automatically account for separately payable processing fees or other charges.
Ask for the Key Facts Statement, or KFS. RBI requires it to include an annual percentage rate, or APR, calculation and the amortisation schedule. APR incorporates interest and applicable charges, making it useful when comparing borrowing costs.
The estimate depends on its assumptions
The calculation assumes the rate and repayment pattern entered. If your agreement allows rate changes, or uses a different payment structure, a single standard estimate will not describe every future payment.
Check the repayment schedule and rate terms before signing.
Prepayment needs a separate check
Do not assume that paying extra will automatically produce the result you expect. Ask the lender how part-payments would affect the outstanding balance, EMI or remaining tenure, and request the applicable terms and charges in writing.
Common Mistakes to Avoid
- Entering the full car price instead of the amount being borrowed.
- Entering five months when you mean five years.
- Choosing a long tenure only because the EMI looks attractive.
- Comparing offers with different loan amounts or repayment periods.
- Treating total interest as the complete cost without checking fees.
- Using an attractive advertised rate as though it were your confirmed offer.
For a fair comparison, keep the loan amount and tenure identical, then examine each offer’s EMI, APR and disclosed charges together. RBI’s KFS framework helps make these costs visible.
Frequently Asked Questions
1. Is a car loan EMI calculator accurate?
It is accurate for the standard formula and inputs used. Your lender’s repayment schedule remains the reference for the actual loan, including its agreed terms and charges.
2. Does using a calculator mean my loan is approved?
No. A calculation estimates repayments; it does not establish approval or confirm the rate you will receive.
3. Does a longer tenure make a loan cheaper?
Not in the examples above. It lowers the monthly EMI but increases total interest because repayment takes longer.
4. Can I use it for a used-car loan?
You can estimate repayments using the same formula when the loan follows a standard monthly EMI structure. Enter the amount, rate and tenure relevant to that offer.
5. Are processing fees included in the EMI?
Do not assume so. Check whether charges are paid upfront or included in the financed amount, and review the KFS for the disclosed costs.
Conclusion
A car loan EMI calculator is most useful when you experiment with it. Compare tenures, test different down payments and look beyond the monthly instalment to total interest.
Before borrowing, match the estimate with your lender’s written offer and your complete ownership budget. The right choice is a car loan you can repay comfortably while keeping room for savings and everyday life.